Bloom Energy and Solaris Energy Poised for Growth Amidst AI Power Demands
Bloom Energy and Solaris Energy are strategically positioned to benefit from the projected 38 gigawatt electricity shortfall tied to AI expansion as companies pivot towards sustainable and decentralized energy solutions.
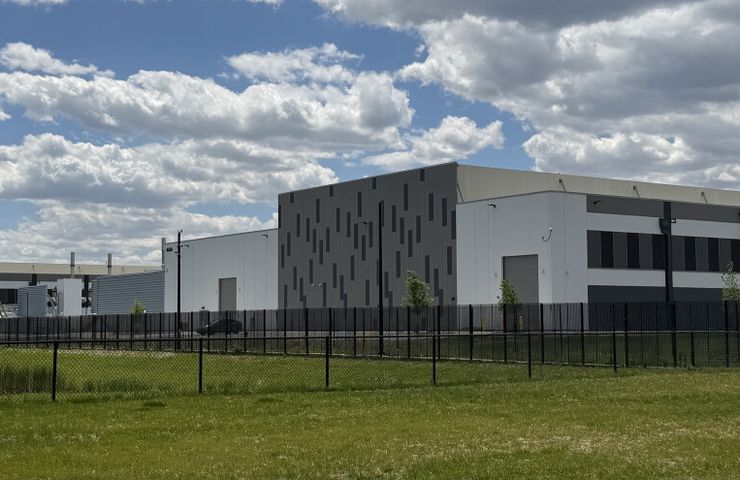
Bloom Energy Corporation and Solaris Energy Infrastructure are strategically positioned to capitalize on the projected electricity shortfall associated with the rapid expansion of artificial intelligence (AI) workloads in the U.S. data center market. Recent insights from Morgan Stanley indicate a significant increase in the estimated net power shortfall from 33 gigawatts to 38 gigawatts for the period spanning 2026 to 2028 due to the surging demand for reliable energy by AI developers. The scale of that revision — five gigawatts — is notable because it compresses the timeline and raises the immediacy of the problem for operators who depend on steady, high-capacity power. Data centers that host AI workloads are not the only consumers affected, but they loom largest in the projections driving demand for supplemental, on-site and distributed generation.
Bloom Energy, a leader in solid-oxide fuel-cell systems, converts various fuels including natural gas and hydrogen into electricity through an electrochemical process, eliminating traditional combustion. The company aims to provide behind-the-meter energy solutions that enable facilities to operate independently from grid constraints. Those systems are intended for installation at customer sites, offering a direct source of power where grid upgrades or new transmission are delayed or unavailable. Meanwhile, Solaris Energy, with its focus on modular natural-gas generation, distribution solutions, and turnkey infrastructure for data centers, also eases the transition to energy independence, particularly in regions facing lengthy grid interconnection delays. Solaris’s approach emphasizes speed of deployment and modular scale. Together, the two firms represent different technical approaches to the same operational problem: how to supply reliable, dispatchable power when the grid cannot keep pace.
Strategic Significance
The partnership between AI developers and energy providers like Bloom and Solaris is critical as the demand for electricity in data centers, which comprised approximately 4.4% of total U.S. electricity consumption in 2023, is expected to rise significantly. The U.S. Department of Energy projects that data centers could account for nearly 12% of the nation’s electricity consumption by 2028. That projection implies a rapid reallocation of grid capacity toward high-performance computing facilities within a few years. For operators, this raises both operational and commercial questions: where will resilient power come from, and who will supply it if traditional utilities cannot expand fast enough?
Onsite generation short-circuits some of that uncertainty. Bloom Energy's capabilities in deploying onsite fuel cells directly at customer sites allow for quick energy access, which is essential for AI applications that require stable power to support their operations. Solar power and batteries can play a role, but fuel cells and modular gas generation offer continuous, dispatchable output without the same footprint or intermittency constraints. Similarly, Solaris has reported a pro forma generation capacity of approximately 2.2 gigawatts by early 2028, signifying its rapid expansion into the distributed power generation sector. That scale—pro forma and forward-looking—signals how quickly non-utility suppliers expect to step into gaps left by slow-moving transmission and distribution upgrades.
Market Dynamics
This energy landscape is further complicated by the current pace of conventional power grid expansion, which is markedly slow, often involving extensive planning and construction timelines. Lengthy permitting processes, right-of-way negotiations and equipment lead times all extend the calendar for new grid capacity. The infrastructure bottleneck presents a lucrative growth avenue for companies able to deliver decentralized energy solutions efficiently. Decentralized models reduce dependence on long-distance transmission and allow power to be staged closer to loads, shortening the time between contract and service.
As AI-driven workloads grow ever more demanding, firms like Bloom and Solaris are well-positioned to profit from this trend. Profitability here is not merely about selling hardware or fuel; it is also about packaging contracting, long-term service, and rapid site deployment into a single, bankable offering for data center operators. The market rewards certainty. Companies that can demonstrate predictable delivery timelines and operational performance stand to capture a larger share of the build-out that Morgan Stanley’s analysis implies.
Adapting Infrastructure
This shift is not limited to established energy companies. Firms such as Cipher Digital, Hut 8, Riot Platforms, and TeraWulf—previously involved primarily in cryptocurrency mining—are also pivoting towards AI infrastructure development, leveraging their existing power assets and capabilities to cater to the emerging demands of high-performance computing workloads. Those companies already manage heavy power loads and have practical experience with colocated generation, power contracts and land use for large computing campuses. Their moves into AI reflect an attempt to redeploy specialized infrastructure toward a higher-demand segment.
As these companies adapt their business models, their existing infrastructures offer a unique advantage. They have established long-term power contracts and significant control over necessary resources like land and transmission access, essential for supporting the demanding electricity requirements of AI centers. Control over those elements reduces a major portion of project risk—risk that otherwise would fall on data center developers or on utilities trying to expand network capacity. For some operators, partnering with firms that already hold these assets may prove faster and more predictable than waiting for grid upgrades.
Conclusion
In summary, the convergence of AI demands and the electricity supply challenge presents a unique market opportunity for energy firms equipped to provide rapid, reliable power solutions. As the landscape evolves, collaborations between energy providers and technology companies will be critical to address the anticipated electricity shortfall effectively. With the potential for profit steeped in quick deployment of solutions, Bloom Energy and Solaris Energy are poised to become pivotal players in this transitioning energy ecosystem. The coming years will test how quickly decentralized providers can move from pro forma capacity and pilot projects to sustained, large-scale operations that meet the uninterrupted power needs of AI developers.