Global investment tops $130 billion as energy security drives growth
Global committed investment in clean hydrogen projects has reached USD 130 billion across over 570 projects, driven by energy security and decarbonization goals, but a policy execution gap must close to realize full capacity.
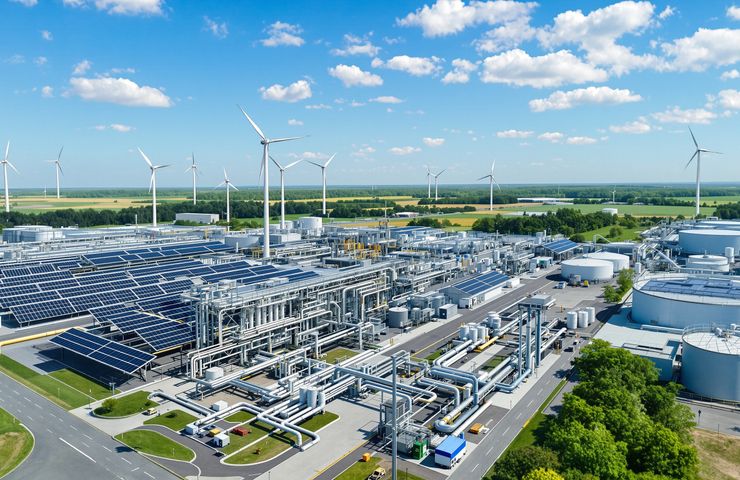
In Tokyo, industry heavyweights gathered for a ministerial meeting co-hosted by the Japanese government, where they brought some eye-opening news from the Hydrogen Council. They revealed that global investment in clean hydrogen projects has soared to about USD 130 billion across more than 570 initiatives. That’s some serious cash flowing into the hydrogen sector!
The Global Hydrogen Compass report lays it all out, tracking investments aimed at supporting around 6.9 million tonnes of clean hydrogen production capacity each year. Out of that, roughly 1.7 million tonnes per year is already up and running—giving us a whopper of a 70% increase in operational capacity within just a year. What's really driving this trend is a noticeable shift where energy security and industrial resilience are starting to compete with decarbonization as key motivators for hydrogen project financing.
You might be wondering how a technology that seemed like it was years away from hitting the big time has managed to attract such a massive influx of investment so quickly. Well, geopolitical tensions impacting oil, gas, and ammonia shipments, particularly through the Strait of Hormuz, have put a spotlight on the vulnerabilities of import-dependent markets. Major consumers in Asia and Europe are now looking to diversify their imports and protect themselves from price shocks—hence, they’re betting big on hydrogen.
Green and Blue Pathways in Focus
When it comes to renewable or green hydrogen production, electrolysis is really leading the pack. China, holding over half of the globe’s renewable projects, accounts for around USD 44.5 billion of the total investment. Europe follows up with near USD 30 billion, thanks to policies like RED III and carbon pricing schemes that are pushing for solid hydrogen infrastructure.
On the flip side, North America is taking the lead in low-carbon or blue hydrogen, which relies on carbon capture and storage (CCS). In fact, over 75% of the world’s low-carbon hydrogen capacity commitments—around 2.9 million tonnes—are centered in the U.S. Gulf Coast. There, tax credits and CO₂ storage sites are driving forward some substantial ammonia and industrial gas projects.
Policy Execution Gap
However, the report sheds light on a concerning “policy execution gap.” While current policies and offtake agreements signal about 6 million tonnes of potential demand by 2030, only around 4.2 million tonnes are secured by binding contracts. Without clear regulatory frameworks and incentive mechanisms—think contracts-for-difference, capacity auctions, or hydrogen blending mandates—many projects might struggle to reach their full potential.
This raises some tough questions: How are developers going to secure offtake agreements in critical sectors like steel, chemicals, and heavy transport? Will governments truly follow through on their hydrogen strategies, or are we looking at potential roadblocks that could stall progress?
Scaling Challenges and Supply Chains
Building giant electrolyzers and steam reformers equipped with CCS isn’t cheap, and with interest rates climbing, financing costs are becoming a real headache. To complicate matters, the expansion of hydrogen storage facilities, pipelines, and import terminals isn’t keeping up with production aspirations. Only a small section of the 40,000 km of proposed pipelines has hit committed status, putting us at risk of stranded assets if supply outstrips infrastructure.
Plus, the global supply chains for electrolyzer components, catalysts, and carbon-capture gear are under strain like never before. Equipment manufacturers are hustling to scale up their production, while project owners are dealing with logistical hiccups for water treatment, compression, and transportation methods.
Beyond Molecules: Ammonia and E-Fuels
Interestingly, the initial wave of projects isn’t just cranking out hydrogen; they’re also feeding into derivative supply chains. Renewable ammonia plants in India and the Middle East are gearing up to export carbon-free fertilizers. Simultaneously, e-methanol projects are teaming electrolysis with CO₂ capture to produce synthetic fuels. For instance, Sinopec’s Kuqa facility uses solar-powered electrolysis to provide green hydrogen for refining, cutting out the gray hydrogen normally used—a promising step towards decarbonizing refining processes.
On top of that, India’s AM Green Kakinada has plans for up to 1 million tonnes of renewable ammonia and has already secured offtake agreements for half of its output. Meanwhile, Denmark’s Kassø E-Methanol project is combining a 52.5 MW electrolyzer with CO₂ capture to churn out 42,000 tonnes annually of e-methanol, specifically targeting the maritime fuel markets, which face strict sulfur regulations and carbon intensity limits.
Financing and Risk Management
With over USD 130 billion on the table, it’s clear investors are confident, yet it also means they have to juggle risks throughout lengthy construction timelines. Rising rates and supply-chain inflation have driven up project costs, leading some lenders to seek more secure offtake assurances or government backing. Investors are now opting to back projects with well-defined pricing frameworks, especially in sectors like steel and chemicals where hydrogen prices directly impact profit margins.
Today's financial advisors highlight the necessity of binding contracts and insurance products tailored for hydrogen ventures, while multilateral development banks are looking into de-risking strategies. This blended finance model could be crucial for closing the policy execution gap and unlocking more capital to achieve mid-decade goals.
Environmental and Social Dimensions
As large-scale electrolyzers and renewable plants come online, they raise critical questions about water and land usage. Electrolysis can guzzle millions of liters of water daily, so careful planning is essential, particularly in water-scarce regions. Plus, massive solar and wind farms need to engage with communities to address land rights and ecological impacts effectively.
On the fossil fuel front, blue hydrogen projects depend on nearly complete CO₂ capture, as any failures could undermine their climate benefits. Advocacy groups are pushing for rigorous monitoring of methane emissions in gas supply chains, insisting on transparency regarding capture rates to ensure real carbon savings instead of perpetuating reliance on fossils.
According to the International Energy Agency’s Global Hydrogen Review, only about 4 million tonnes of low-emission hydrogen capacity is firmly set to roll out by 2030, despite lofty targets. This really highlights that clear policies are just as crucial as engineering skill in pushing the hydrogen agenda forward.
A Market in Transition
The current hydrogen landscape is anything but uniform. Countries like Japan and Korea are leaning toward importing ammonia and liquid carriers to offset domestic fuel gaps, while nations such as the EU and the U.S. are advocating for local production to bolster their heavy industries. Each approach influences infrastructure layout, from port facilities and shipping methods to hydrogen pipelines and storage solutions.
This tug-of-war among national strategies, trade flows, and cross-border projects indicates that hydrogen is carving out a unique niche in the global energy framework—one that bridges electrons and molecules, connecting renewable energy to sectors that are tough to electrify.
About the Hydrogen Council: Established in 2017, the Council serves as a global industry platform representing a variety of stakeholders dedicated to hastening the deployment of clean hydrogen across the value chain. Their insights and metrics are invaluable resources for investors, media, and policymakers around the globe.